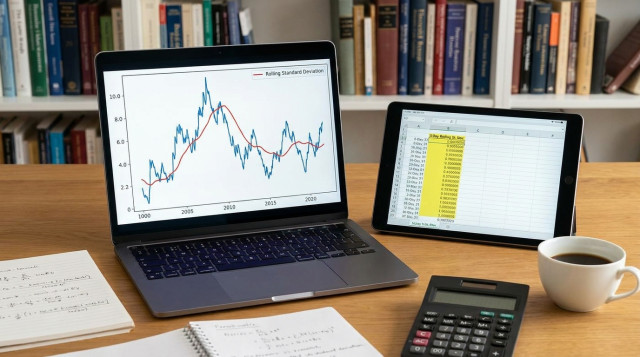
how to compute rolling standard deviation for a time series
Rolling standard deviation (also called moving or windowed standard deviation) measures how spread out values are within a fixed-size window that moves along a time series. It helps identify periods of high or low volatility, detect changes in variability, and smooth noisy signals for analysis or trading strategies.
what is rolling standard deviation and when to use it
Unlike a single standard deviation computed for an entire dataset, the rolling standard deviation reports a value for each point using the most recent N observations (the window). Use it when you need a local estimate of variability over time—examples: financial returns volatility, sensor noise levels, or variability in daily demand.
formula for rolling standard deviation
For a window of size N with observations x_{t-N+1}, ..., x_t, the sample rolling standard deviation at time t is:
s_t = sqrt( (1/(N-1)) * sum_{i=0}^{N-1} (x_{t-i} - mean_t)^2 )
where mean_t is the mean of values inside the window:
mean_t = (1/N) * sum_{i=0}^{N-1} x_{t-i}
For a population-style estimate (divide by N instead of N-1) replace 1/(N-1) with 1/N. Choose sample or population depending on whether your window is considered a sample of a larger process.
step-by-step method to compute manually
- Choose a window size N (e.g., 5, 20, 30). Larger N smooths variability but reacts slower to changes.
- For the first window (times 1..N), compute the window mean: mean_N = (x1 + ... + xN)/N.
- Compute squared deviations: (xi - mean_N)^2 for i=1..N and sum them.
- Divide the sum by (N-1) for a sample standard deviation; take the square root to get s_N.
- Move the window forward one step: drop x1, include x_{N+1}. Recompute the mean and s_{N+1} using the new set x2..x_{N+1}.
- Repeat until you reach the end of the series. Each time t >= N you obtain s_t.
rolling standard deviation: worked example with numbers
Suppose daily returns (in %) for 8 days: 0.5, -0.2, 0.8, -0.1, 0.3, 0.4, -0.6, 0.2. Compute a 3-day rolling standard deviation (N=3) using sample formula.
| Day | Window values | Mean | Variance (sum sq dev/(N-1)) | Std dev |
|---|---|---|---|---|
| 3 | 0.5, -0.2, 0.8 | 0.3667 | 0.3356 | 0.5793 |
| 4 | -0.2, 0.8, -0.1 | 0.1667 | 0.3856 | 0.6211 |
| 5 | 0.8, -0.1, 0.3 | 0.3333 | 0.3600 | 0.6000 |
| 6 | -0.1, 0.3, 0.4 | 0.2000 | 0.1450 | 0.3808 |
| 7 | 0.3, 0.4, -0.6 | 0.0333 | 0.3267 | 0.5716 |
| 8 | 0.4, -0.6, 0.2 | 0.0000 | 0.2200 | 0.4690 |
Interpretation example: on day 6 the 3-day standard deviation is 0.38% → recent returns were less volatile than on day 4 (0.62%).
efficient rolling computation (online formulas)
Recomputing means and squared deviations from scratch for large series is costly. Use a rolling update:
- Maintain running sums: S1 = sum of x in window, S2 = sum of x^2 in window.
- mean = S1 / N; variance = (S2 - N*mean^2) / (N-1).
- When the window moves: subtract old value x_old from S1 and x_old^2 from S2; add x_new and x_new^2.
This method avoids iterating inside the window and is numerically stable for typical ranges. For very small differences or very large values, use specialized numerically stable algorithms (Welford's method adapted for windows).
how to choose window size and sample vs population
Pick N based on the time-scale of interest: short windows (5-10) for high-frequency changes; medium (20-50) for weekly/monthly smoothing; long (100+) for structural variability. Use sample formula (divide by N-1) when you treat the window as a sample drawn from a larger process. Use population (divide by N) when the window fully represents the population you care about.
common pitfalls and mistakes
- Using too small N increases noise and false positives for volatility spikes.
- Using too large N delays detection of real changes.
- Failing to handle missing data: decide whether to skip windows with missing values or to impute them.
- Mixing sample and population formulas inconsistently across systems leads to small but important differences.
- Numerical instability when subtracting large close numbers—use running algorithms or higher-precision types.
example: compute rolling standard deviation in a spreadsheet
In Excel or Google Sheets, with data in column A (rows 2..1001) and window N in cell B1:
- Use AVERAGE to compute rolling mean: in C2 enter: =AVERAGE(OFFSET(A2,0,0,$B$1)) and drag down.
- Use STDEV.S for sample rolling stdev: in D2 enter: =STDEV.S(OFFSET(A2,0,0,$B$1)) and drag down.
- Or use array formulas like =SQRT((SUMSQ(range)-COUNT(range)*AVERAGE(range)^2)/(COUNT(range)-1)).
Note: OFFSET is volatile and can slow large sheets; prefer INDEX-based ranges for performance if available.
how to use an online calculator or tool
Calculatorr offers tools and calculators for statistical measures. To use an online rolling standard deviation tool:
- Input or paste your time series values (comma or newline separated).
- Specify the window size N and choose sample/population option.
- Run the calculation to get a series of stdev values aligned to each time t (usually starting at t=N).
- Download results or copy them back to your spreadsheet for charts.
Visit https://calculatorr.com/ to find relevant statistical calculators and guides that speed up this workflow.
interpreting rolling standard deviation results
A rising rolling standard deviation signals increasing short-term variability—possible regime change, event-driven noise, or higher volatility. A falling value implies stabilization. Use alongside moving average trends to separate signal from amplified noise. Compare rolling stdev across different N to check persistence: if spikes persist for long windows, the change is structural; if only short windows spike, it's transient noise.
visualizing rolling standard deviation
Plot the original time series and overlay a secondary axis with rolling standard deviation. Common patterns to watch for:
- Volatility clustering: periods where stdev stays elevated.
- Spikes after shocks: sudden peaks followed by decay.
- Seasonal variability: repeating patterns in stdev indicating cyclical behavior.
final practical tips
- Check edge handling: most implementations output stdev only for t>=N; decide how to treat leading points (NA, smaller windows, or padding).
- When comparing assets or sensors, normalize stdev by mean magnitude if relative variability matters (coefficient of variation = stdev/mean).
- Combine with other rolling metrics (mean, skewness, kurtosis) to get a fuller view of distributional changes.
If you need a ready-to-use tool, explore the statistical calculators and time-series guides at https://calculatorr.com/ to compute rolling standard deviation quickly and export the results for analysis.