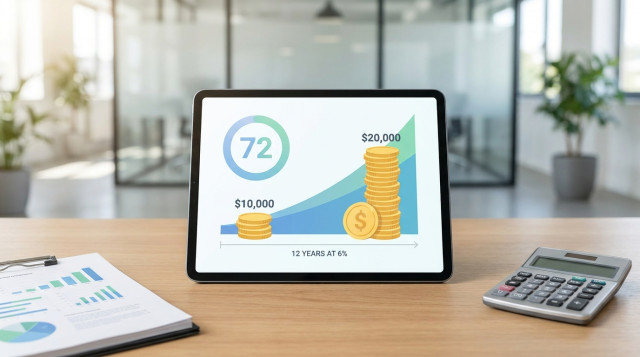
A rule of 72 calculator answers one of the most common money questions: how many years will it take for an investment, a debt or the price of everyday goods to double? The rule gives you a fast estimate with one division and no spreadsheet. It works at the kitchen table, in a meeting or while comparing two savings options.
This guide explains the formula, shows how to apply it manually, tests its accuracy against the exact math and covers the situations where it helps most: investing, inflation, fees and debt. If you prefer to skip the arithmetic, you can also run your numbers with the tools on Calculatorr.
What is the rule of 72 and what does it tell you?
The rule of 72 is a mental shortcut that estimates the number of years required for a value to double when it grows at a fixed annual rate with compounding. It does not tell you your final balance. It tells you the doubling time, which is often the most useful number for comparing options quickly.
The rule applies to anything that grows by a percentage each year: a savings account, a stock portfolio, a bond fund, a loan balance with unpaid interest or consumer prices under inflation.
Why the number 72?
The exact doubling time comes from logarithms. Dividing ln(2), about 0.693, by the periodic growth rate gives the answer. The number 72 is a convenient approximation because it is close to 69.3 adjusted upward for typical interest rates, and it divides evenly by 1, 2, 3, 4, 6, 8, 9 and 12. That makes mental math easy for the most common rates.
Rule of 72 formula: how to estimate years to double
The formula is simple:
Years to double = 72 / annual rate (in percent)
Use the rate as a whole number, not a decimal. For 8%, divide by 8, not by 0.08.
- At 4%: 72 / 4 = 18 years
- At 6%: 72 / 6 = 12 years
- At 9%: 72 / 9 = 8 years
- At 12%: 72 / 12 = 6 years
Rearranged formulas you can also use
- Rate needed = 72 / years to double. If you want to double your money in 10 years, you need about 7.2% per year.
- Tripling time = 114 / rate. At 6%, money triples in roughly 19 years.
- Quadrupling time = 144 / rate. At 6%, money quadruples in about 24 years, which is two doublings.
How to use the rule of 72 step by step
Follow these steps whenever you need a quick estimate:
- Identify the annual growth rate as a percentage. Use the effective annual rate if interest compounds more than once per year.
- Divide 72 by that percentage.
- Read the result as the years needed for the amount to double.
- For further doublings, multiply the result by the number of times you want to double.
Example 1: savings that double
You invest $10,000 at an average return of 6% per year.
72 / 6 = 12 years. After about 12 years you would have roughly $20,000. After 24 years, two doublings, roughly $40,000. The exact figures are $20,122 after 12 years and $40,489 after 24 years, so the shortcut is very close.
Example 2: how long does retirement money take to double?
A retirement account earns 8% annually and currently holds $50,000.
72 / 8 = 9 years. The balance reaches about $100,000 in 9 years and about $200,000 in 18 years, assuming no withdrawals and no extra contributions. Regular contributions would speed this up, which you can model with a compound interest calculator.
How to find the rate needed to double money in a set time
The rule also works in reverse. Suppose you want to double a down payment fund in 6 years.
72 / 6 = 12% per year. That is a demanding target, and it signals that you probably need to increase contributions rather than depend on returns alone.
Now try a more modest goal: doubling in 10 years. 72 / 10 = 7.2%. The exact rate is 2^(1/10) - 1 = 7.18%, so the shortcut is almost perfect.
Rule of 72 vs exact formula: how accurate is it?
The exact doubling time is t = ln(2) / ln(1 + r), where r is the annual rate as a decimal. The table compares both methods.
| Annual rate | Rule of 72 (years) | Exact (years) |
|---|---|---|
| 2% | 36.0 | 35.0 |
| 3% | 24.0 | 23.5 |
| 4% | 18.0 | 17.7 |
| 5% | 14.4 | 14.2 |
| 6% | 12.0 | 11.9 |
| 8% | 9.0 | 9.0 |
| 10% | 7.2 | 7.3 |
| 12% | 6.0 | 6.1 |
| 15% | 4.8 | 5.0 |
The rule is most accurate between about 6% and 10%. At low rates, 70 or 69.3 can give slightly better results. At very high rates, such as 30% or more, the rule starts to drift and the exact formula is the safer choice.
Rule of 72 for inflation: when does purchasing power halve?
The same logic shows how fast your money loses value. If inflation averages 3% per year, prices double in about 72 / 3 = 24 years. Put differently, cash that buys 100 units of goods today buys about 50 units in 24 years.
At 4% inflation, purchasing power halves in 18 years. This is why money kept idle for decades can lose a large part of its real value even though the balance never decreases.
Comparing returns with inflation
If your savings earn 5% and inflation is 3%, your real growth is close to 2%. Your real purchasing power doubles in about 36 years, not 14. For a precise adjustment, use the real rate of return rather than the nominal rate.
How fees and debt change the doubling time
Small percentage differences have a large effect over decades. Compare two funds with the same gross return of 7%:
- Fund A charges 0.2%, so net return is 6.8%. 72 / 6.8 = about 10.6 years to double.
- Fund B charges 1.2%, so net return is 5.8%. 72 / 5.8 = about 12.4 years to double.
That gap of nearly two years per doubling adds up. Over 30 years, Fund A completes almost three doublings while Fund B completes fewer than two and a half.
Using the rule on debt
The rule is equally useful on the other side of the balance sheet. A credit card balance with a 24% annual rate that you never pay down doubles in roughly 72 / 24 = 3 years. Because most cards compound monthly, the real figure is slightly shorter. This is a quick way to see why carrying high-interest balances is so costly.
Common mistakes when using the rule of 72
- Using the decimal rate. Dividing 72 by 0.06 gives 1,200, which is meaningless. Use 6.
- Applying it to simple interest. The rule assumes compounding. With simple interest, doubling takes 100 / rate years.
- Ignoring taxes and fees. Use the net rate after costs for a realistic estimate.
- Treating average returns as guaranteed. A portfolio averaging 8% will not earn exactly 8% each year. The result is an estimate, not a promise.
- Using it for extreme rates. Below 2% or above 20%, check the answer with the exact formula.
- Forgetting withdrawals and contributions. The rule assumes no money is added or removed.
How to use a rule of 72 calculator online
An online calculator removes the mental math and also lets you compare the shortcut with the exact result. The workflow is straightforward:
- Enter the expected annual rate, using the net rate after fees if possible.
- Choose whether you want years to double, or the rate needed for a target number of years.
- Review the estimate and compare it with the exact logarithmic result.
- Adjust the rate to test optimistic, realistic and conservative scenarios.
You can find related tools for growth, interest and percentage work at Calculatorr. Running three scenarios, such as 4%, 6% and 8%, is often more useful than relying on a single number.
How to interpret the rule of 72 result
A doubling time is a planning signal. If the result is 9 years, you know a lump sum invested today could roughly quadruple in 18 years and grow eightfold in 27, all else equal. If it is 36 years, the growth is too slow to reach most goals without larger contributions.
Use the result to ask practical questions. Is the time horizon long enough for the rate you expect? Do fees take too much of the return? Does inflation erase most of the gain? A quick estimate is often enough to decide whether a deeper calculation is worth doing.
For decisions involving specific amounts, such as loan offers or retirement targets, use the rule as a first filter and then confirm with the exact formula. The shortcut keeps you fast, and the exact math keeps you accurate.