how to calculate sinking fund contribution for a future expense
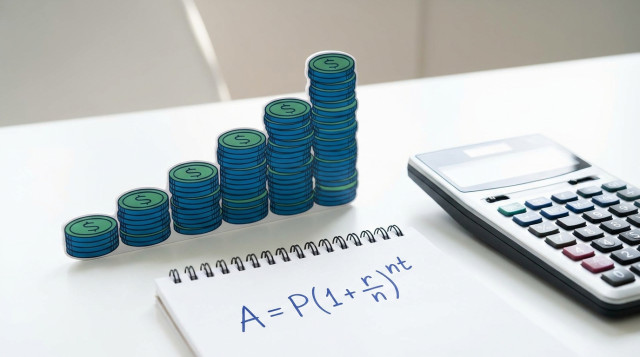
A sinking fund is a planned savings account set aside to pay for a known future expense (equipment replacement, a down payment, taxes, or a major repair). Knowing how to calculate sinking fund contribution helps you budget reliably and avoid large, one-off payments. This guide explains what a sinking fund is, shows the formula, walks through manual steps, gives practical numeric examples, and explains how to use an online calculator effectively.
what is a sinking fund and when to use it
A sinking fund is regularly scheduled savings targeted at a specific goal and date. Unlike emergency funds (for unknown shocks), sinking funds are for planned, predictable costs. Use a sinking fund when you know the amount needed and the timeframe — for example, saving $6,000 for a new HVAC unit in 18 months, replacing a laptop in two years, or accumulating annual insurance premiums.
formula: how to calculate sinking fund contribution
Main keyword: how to calculate sinking fund contribution appears here and in the heading. The basic formulas depend on whether you expect to earn interest on the saved amount.
1) Without interest (simple savings)
Contribution per period = Target amount ÷ Number of periods
2) With interest (regular deposits, compounded each period)
When you deposit at the end of each period and interest compounds at rate r per period, use the future value of an ordinary annuity formula solved for the deposit:
Deposit per period = Target amount × [r / ((1 + r)^n - 1)]
Where:
- r = interest rate per period (decimal). If you expect annual interest and save monthly, r = annual rate / 12.
- n = total number of deposits (periods).
If deposits occur at the start of each period (annuity due), multiply the ordinary annuity deposit by 1/(1+r) to adjust, or equivalently divide the target by ((1+r)^n - 1) × (1+r)/r and solve for deposit.
step-by-step manual calculation
step A — define the target and timeframe
- Target amount (T): the exact cash needed at the future date.
- Timeframe: how long until the expense (years or months).
- Deposit frequency: monthly, quarterly, or yearly.
step B — decide if interest applies
If the money will sit in an interest-bearing account (savings account, money market, short-term bond), use the interest formula. If it will sit under a mattress or you ignore interest, use the simple division method.
step C — convert rates and periods
- Convert annual interest rate to rate per period: r = annual_rate / periods_per_year.
- Calculate total number of deposits: n = years × periods_per_year.
step D — compute the periodic deposit
If no interest: deposit = T ÷ n.
If interest: deposit = T × [r / ((1 + r)^n - 1)]. Use a calculator to compute (1 + r)^n accurately.
practical examples with numbers
example 1 — replace a roof in 5 years (no interest)
Target: $15,000. Timeframe: 5 years. Deposit frequency: monthly. n = 5 × 12 = 60.
Deposit per month = 15,000 ÷ 60 = $250 per month.
Interpretation: Saving $250 each month will give you $15,000 after 5 years (ignoring interest).
example 2 — save for new car in 3 years with interest (monthly deposits)
Target: $12,000. Annual expected interest: 1.8% (typical high-yield savings). Monthly rate r = 0.018 ÷ 12 = 0.0015. n = 3 × 12 = 36.
Deposit per month = 12,000 × [0.0015 / ((1 + 0.0015)^36 - 1)].
Compute (1 + r)^n = (1.0015)^36 ≈ 1.0551. Then denominator = 1.0551 - 1 = 0.0551.
Deposit = 12,000 × (0.0015 / 0.0551) ≈ 12,000 × 0.02722 ≈ $326.64 per month.
Interpretation: Because interest adds a small amount, you need about $326.64 each month instead of $333.33 (which would be 12,000/36). Interest reduces required savings slightly.
example 3 — quarterly contributions for equipment in 2 years (annuity due)
Target: $8,000. Annual interest expected: 2.4%. Contributions at the start of each quarter. Periods per year = 4, r = 0.024/4 = 0.006. n = 2 × 4 = 8.
Ordinary annuity deposit = 8,000 × [0.006 / ((1.006)^8 - 1)]. Compute (1.006)^8 ≈ 1.0493; denom = 0.0493. Ordinary deposit ≈ 8,000 × (0.006 / 0.0493) ≈ 8,000 × 0.1217 ≈ $973.60.
Because deposits are at the start of each period (annuity due), divide ordinary deposit by (1 + r): deposit_due ≈ 973.60 ÷ 1.006 ≈ $967.42 per quarter.
Interpretation: Start-of-period deposits slightly reduce the per-period amount because each deposit immediately accrues interest.
using an online sinking fund calculator
An online calculator speeds up the math: enter target amount, timeframe, contribution frequency, expected annual interest, and whether deposits are at period start or end. The tool returns the periodic payment and the accumulated total. For convenience, use the calculators on https://calculatorr.com/ to test multiple scenarios quickly and compare contributions with and without interest.
how to interpret results and plan
- If the required contribution is higher than you can afford, consider increasing the timeframe, reducing the target, or seeking a higher-yield (but safe) account.
- Compare monthly deposits to your budget: if a sinking fund competes with high-interest debt, prioritize paying down debt first unless the expense is imminent and unavoidable.
- Review interest assumptions: small changes in expected rate have limited impact for short term goals; for long horizons they matter more.
- Label separate sinking funds: tracking multiple goals in distinct accounts prevents accidental spending and improves clarity.
common errors and how to avoid them
- Mixing compounding frequencies: ensure interest rate per period matches deposit frequency (monthly deposits use monthly rate).
- Rounding early: keep intermediate calculations precise and round only final result to cents.
- Ignoring fees and inflation: account fees or inflation reduce real value; for long-term goals, factor in expected inflation if precision matters.
- Assuming high returns: don’t count on risky investments to fund short-term sinking funds; use low-risk accounts for predictable outcomes.
- Forgetting timing: deposits at period start (annuity due) and end (ordinary) change required amounts; choose the model matching your plan.
quick checklist to create a sinking fund
- Define objective and exact target amount.
- Choose timeframe and deposit frequency.
- Decide whether to place money in an interest-bearing account and estimate realistic annual return.
- Calculate periodic deposit using the formulas above or an online calculator on https://calculatorr.com/.
- Automate transfers to a dedicated account and label it with the goal and target date.
- Review every 6–12 months and adjust for changes in costs or schedule.
useful table: quick reference for monthly deposits (no interest)
| Target | Timeframe | Monthly deposit |
|---|---|---|
| $3,600 | 1 year | $300 |
| $6,000 | 2 years | $250 |
| $10,000 | 3 years | $277.78 |
| $20,000 | 5 years | $333.33 |
final tips for reliable sinking funds
- Automate deposits the day after payday to ensure consistency.
- Keep sinking funds separate from daily-checking to reduce temptation.
- Revisit goals if actual costs change; adjust contributions rather than drain other funds.
- Use conservative interest estimates to avoid shortfalls.
Applying these steps you can accurately calculate the contribution needed for any planned expense and keep your finances predictable. For fast calculations and scenario comparisons, try a sinking fund calculator at https://calculatorr.com/ and adapt the numbers to your budget.