how to calculate contribution margin is essential for pricing, profitability analysis and short-term decision making. The contribution margin shows how much revenue from each sale is available to cover fixed costs and generate profit after covering variable costs. This guide explains what the contribution margin is, the formulas, how to calculate it manually, how to use it to set prices and make decisions, and how to use an online calculator to speed the process.
how to calculate contribution margin: definition and when to use it
The contribution margin is the difference between a product's sales price and the variable cost per unit. It can be expressed in absolute terms (currency per unit) or as a percentage of sales (contribution margin ratio). Use it when you need to:
- Set or adjust prices
- Decide whether to accept a special order
- Estimate break-even volume
- Allocate resources among products
formulas you need
Absolute contribution margin (per unit):
Contribution margin per unit = Selling price per unit − Variable cost per unit
Contribution margin ratio (percentage):
Contribution margin ratio = (Contribution margin per unit / Selling price per unit) × 100
Break-even units (useful downstream):
Break-even units = Total fixed costs / Contribution margin per unit
how to calculate contribution margin manually: step-by-step
- Identify selling price per unit. The actual price you charge customers for one unit.
- List variable costs per unit. Include direct materials, direct labor (if variable), sales commissions, packaging, shipping variable portion, and any other cost that changes with volume.
- Subtract variable cost from selling price. The result is contribution margin per unit.
- Calculate contribution margin ratio. Divide the per-unit margin by the selling price and multiply by 100 to get a percentage.
- Interpret the result. Higher values mean more of each sale contributes to fixed costs and profit.
worked numeric example (single product)
Assume a product sells for $50 per unit. Variable costs are: materials $12, direct labor $8 (variable portion), packaging $2, and sales commission $3. Total variable cost per unit = $25.
- Contribution margin per unit = $50 − $25 = $25
- Contribution margin ratio = ($25 / $50) × 100 = 50%
Interpretation: For every unit sold, $25 goes to cover fixed costs and profit. With a 50% contribution margin ratio, half of revenue contributes to fixed costs and profit.
use contribution margin to find break-even
If fixed costs are $10,000 per month, break-even units = $10,000 / $25 = 400 units. So you must sell 400 units to cover all costs; sales above that generate profit.
how to use contribution margin for pricing and decision making
Contribution margin helps determine minimum acceptable price for special orders, the impact of discounts, and which products are most profitable to prioritize.
setting a minimum acceptable price for a special order
For a one-time order that doesn't affect fixed costs or regular sales, the minimum acceptable price is the variable cost per unit (or slightly higher to contribute to overhead). Example: if variable cost is $25, a one-off order below $25 loses money on each unit. If fixed capacity is unused and no cannibalization occurs, pricing just above $25 might be acceptable.
evaluating discounts and promotions
Calculate how a discount affects contribution margin ratio. Example: a 10% discount reduces selling price from $50 to $45, contribution margin per unit becomes $45 − $25 = $20 (ratio 44.4%). Check whether reduced margin still covers fixed costs at forecasted volumes.
product mix and prioritization
Compare contribution margins across products to decide which to promote or allocate scarce capacity to. A high-margin product delivers more contribution per unit of capacity than a low-margin product, even if revenue is lower.
how to calculate contribution margin for multiple products and weighted margin
When selling several products with different prices and costs, compute each product's contribution margin and then a weighted average based on sales mix.
weighted contribution margin example
Product A: price $40, variable cost $15 → margin $25. Product B: price $80, variable cost $60 → margin $20.
If expected sales mix is 60% A and 40% B by units, weighted contribution margin per unit = (0.6 × $25) + (0.4 × $20) = $23.
Use weighted margin to calculate overall break-even: Break-even units = Total fixed costs / Weighted contribution margin.
how to use an online calculator to compute contribution margin
Use an online contribution margin calculator to speed recurring analysis. Typical inputs: selling price, variable cost per unit, fixed costs, and sales mix for multiple products. The calculator returns contribution margin per unit, margin ratio, break-even units and revenue, and sensitivity analysis for price changes.
Visit the calculators on Calculatorr to try a contribution margin and break-even calculator. Enter your numbers to see instant results and test price or cost changes.
interpretation: what different results mean
- High contribution margin per unit and ratio: Strong direct profitability per sale; fewer units required to break even.
- Low contribution margin: Business needs higher volume or cost reductions; pricing power is limited.
- Negative contribution margin: Variable costs exceed price — selling loses money on every unit and should be stopped unless strategy justifies it (e.g., loss leader with careful limits).
common errors to avoid when calculating contribution margin
- Including fixed costs as variable costs: fixed costs should not be part of per-unit variable cost.
- Ignoring semi-variable costs: split mixed costs into fixed and variable components before calculation.
- Using list prices instead of net realized prices: use actual selling price after discounts and returns.
- Assuming variable costs are constant at all volumes: volume discounts or overtime labor can change variable cost per unit.
quick checklist before final decisions
- Confirm all variable cost items are included and accurately measured.
- Use realistic sales mix for weighted margin calculations.
- Test sensitivity: change price and variable cost by realistic ranges to see impact on break-even.
- Cross-check results with an online calculator at Calculatorr for speed and accuracy.
two concise examples for practice
| Scenario | Selling price | Variable cost | Contribution/unit | Margin % |
|---|---|---|---|---|
| Example 1 | $100 | $60 | $40 | 40% |
| Example 2 | $30 | $20 | $10 | 33.3% |
Use these examples to confirm manual calculations match an online calculator output. If they differ, re-check which costs were categorized as variable.
Image suggestions:
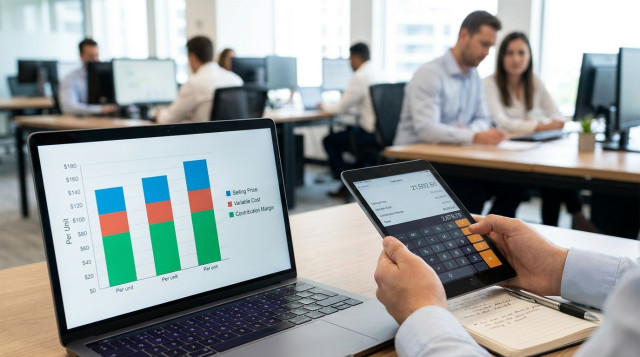
- Place a chart near the "worked numeric example" section showing price, variable cost and contribution split in a stacked bar. Alt text: 'contribution margin breakdown chart showing selling price, variable cost and contribution margin'.
- Place a table or infographic near the "how to use an online calculator" section illustrating inputs and outputs. Alt text: 'input fields and outputs of a contribution margin calculator showing price, variable cost, margin and break-even'.
Calculating contribution margin is a practical, repeatable step that clarifies pricing decisions and profitability. Use the formulas above, test with realistic scenarios, and run numbers quickly with the tools on Calculatorr to make data-driven choices.